What this result means
The figure is a starting point, not a standard. There is no authoritative dataset that establishes a correct allowance by age, and anyone presenting one usually is not citing anything.
What makes an allowance work is that it is predictable and that your child genuinely controls it. An amount that is slightly too small but paid every week without fail teaches far more than a larger amount paid when you remember.
If your child spends it all immediately and feels no trade-off, the allowance probably covers too little. Move something onto their budget rather than raising the number.
How it works
- Take your child’s age in years.
- Multiply by the chosen weekly rate: half their age, their age, or one and a half times their age.
- Optionally round to a whole amount, which is what most families do in practice.
- Multiply by the period: weekly as is, monthly by 4.33, or yearly by 52.
- Apply the suggested split of 50% spend, 40% save, and 10% give.
A worked example
- A 10-year-old at the standard rate: 10 × $1.00 = $10 a week.
- Over a year that is $520.
- Split 50/40/10: $5.00 to spend, $4.00 to save, $1.00 to give.
- Shown monthly, $10 a week becomes about $43.33.
Assumptions and limits
- The dollar-per-year-of-age convention is a widely repeated rule of thumb, not a researched benchmark.
- The 50/40/10 split is also a convention. Its value is making saving automatic rather than a weekly decision.
- No inflation adjustment is applied, and no regional cost-of-living adjustment.
- It assumes a regular allowance rather than ad hoc payments, which are much harder to learn from.
Sources
- Last reviewed
- October 1, 2026
- Geography
- United States
No dataset is cited because none supplies these figures. Both the rate and the split are conventions, and are labelled as conventions.
Common questions
What age should we start an allowance?
Most families find it starts working around six or seven, when a child can hold a savings goal in mind for more than a few days. Earlier is not harmful, it just teaches less.
Should the allowance be tied to chores?
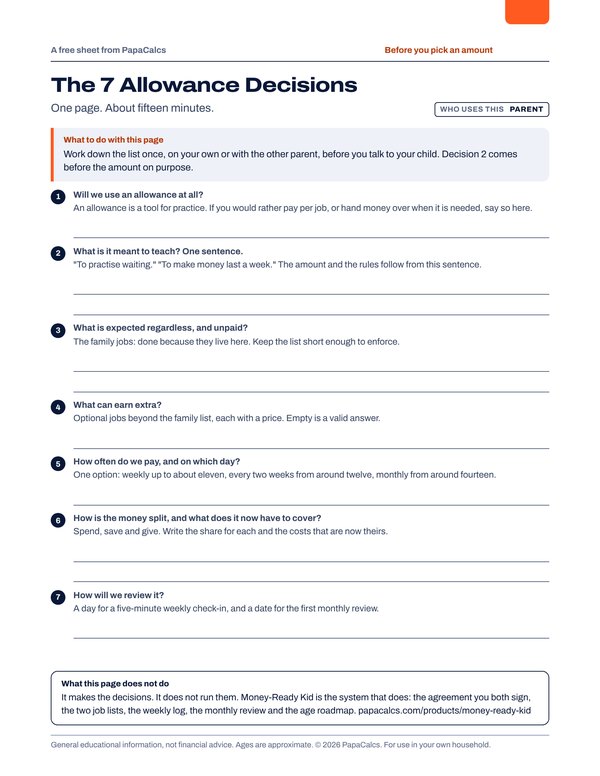
Usually not for everyday family chores. A baseline of unpaid responsibilities with optional paid extras on top tends to hold up better than paying for ordinary help.
Is a dollar per year of age still reasonable?
As a starting point, yes, though it is a convention rather than an indexed figure. What matters more is whether the amount is large enough that choosing between two things is a real decision.
Should I make saving compulsory?
Making it automatic works better than making it a rule they have to remember. Whether it is compulsory is a values decision, but automatic beats optional either way.